After an offer is accepted, due diligence helps California buyers thoroughly review the property, paperwork, and financing before closing.
Getting your offer accepted is always good news, but there’s still a few more things to do before the home is officially yours.
You’ll need to review documents, check the property’s condition, work through financing, address any issues, and make sure you’re comfortable with everything before sealing the deal.
And if you’re the seller, this due diligence phase is just as important. Staying organized, sharing necessary information, and responding quickly to questions can help keep your sale running smoothly.
Here are the key steps in real estate due diligence in California that both buyers and sellers should know.
Table of Contents:
- Open escrow and submit the deposit
- Review the preliminary title report
- Review the seller’s disclosures carefully
- Inspect the property carefully
- Complete the appraisal
- Take your loan to final approval
- Stay on top of contingency deadlines
- Negotiate what matters
- Complete the final walkthrough
- Sign, fund, and close escrow
- Get guidance on real estate due diligence in California
1. Open escrow and submit the deposit
After the offer is accepted, escrow is opened according to the purchase agreement and local practice. According to the California Department of Real Estate (DRE), the seller generally opens escrow, although the buyer can also do so. Escrow then holds the transaction’s funds and documents while both sides work toward closing.
What the buyer does:
- Submit the deposit required by the purchase agreement
- Review and sign escrow instructions
- Provide any information or documents escrow requests
- Keep track of contingency and other contract deadlines
What the seller does:
- Open escrow, in most cases
- Review and sign escrow instructions
- Provide requested ownership and payoff information, when applicable
- Complete and deliver required disclosures
- Respond to escrow or transaction-related requests
2. Review the preliminary title report
The preliminary title report can flag recorded issues that could affect ownership or how you use the property, including liens, easements, restrictions, and other exceptions. It’s also worth remembering that the report itself isn’t a title insurance policy.
What the buyer does:
- Review the preliminary title report with their agent
- Look closely at liens, easements, restrictions, and other recorded exceptions
- Ask questions about anything that could affect ownership, access, or future plans for the property
- Consult a real estate attorney or other appropriate professional if an issue needs legal interpretation
- Review the proposed title insurance coverage and exclusions
What the seller does:
- Provide any ownership or title-related documents requested during escrow
- Work to clear liens or other title issues that must be resolved before closing
- Respond to questions about recorded matters affecting the property
- Provide payoff information when there’s an existing mortgage or other lien to be satisfied
3. Review the seller’s disclosures carefully
In many California residential sales, sellers must provide a Transfer Disclosure Statement (TDS), along with a Natural Hazard Disclosure Statement and other disclosures that apply to the property or transaction.
What the buyer does:
- Review the TDS and other disclosures carefully
- Note past water intrusion, roof or structural repairs, additions, solar equipment, or other significant conditions
- Ask follow-up questions when something is unclear or incomplete
- Bring in an appropriate inspector or specialist when a disclosure raises a concern
- Review HOA documents and other property-specific information, when applicable
What the seller does:
- Complete all required disclosures accurately and on time
- Disclose known material facts that could affect the property’s value or desirability
- Provide information about past repairs, damage, additions, or other known conditions
- Supply any additional documents required for the property or transaction
- Respond promptly if the buyer asks for clarification or supporting information
4. Inspect the property carefully
Even a seemingly perfect home deserves a closer inspection. A general home inspection evaluates many of the home’s accessible systems and components, but particular concerns may call for specialists.
What the buyer does:
- Schedule the general home inspection within the contract timeline
- Review the inspector’s findings carefully
- Bring in specialists when needed for areas such as the roof, foundation, sewer line, HVAC, pool, chimney, drainage, or solar equipment
- Ask for estimates when a significant repair could affect the purchase decision
- Decide whether to accept the property as is, request repairs or credits, or take another step allowed by the contract
What the seller does:
- Provide reasonable access for scheduled inspections
- Make sure agreed-upon areas and systems are accessible for inspection
- Respond to follow-up questions about known property conditions
- Review any repair or credit requests that come out of the inspection process
- Complete any agreed-upon repairs before closing
5. Complete the appraisal
If you’re financing the purchase, the lender will usually require an appraisal to estimate the property’s market value. It’s separate from the home inspection, and even a satisfactory appraisal doesn’t guarantee final loan approval.
What the buyer does:
- Work with the lender as the appraisal is ordered and completed
- Review the appraisal once it’s available
- Stay in touch with the lender about any appraisal-related conditions
- If the value comes in below the purchase price, discuss the available options with the lender and agent
- Keep the appraisal contingency and its deadline in mind, if one applies
What the seller does:
- Provide access to the property for the appraiser
- Make sure the appraiser can reasonably access the areas that need to be viewed
- Provide relevant property information through the agent when appropriate, such as permitted improvements or recent upgrades
- If the appraisal comes in low, consider any renegotiation or other response allowed under the contract
6. Take your loan to final approval
Preapproval gets the financing process started, but it isn’t final loan approval. As you move through the real estate closing process in California, your lender continues underwriting both you and the property, so you’ll need to stay responsive and avoid financial changes that could complicate the loan.
What the buyer does:
- Provide updated income, employment, bank, or asset documents when requested
- Explain any financial transactions the underwriter flags
- Secure homeowners insurance
- Avoid taking on new debt or making major financial changes without first checking with the lender
- Review the Closing Disclosure and compare it with the Loan Estimate
- Ask about any unexpected changes in the loan terms or closing costs
For most covered mortgages, the lender must provide the Closing Disclosure at least three business days before closing, giving the buyer time to review the final loan terms and costs.
What the seller does:
- Keep the transaction moving while the buyer completes financing
- Provide access or property-related information if the lender or appraiser needs anything further
- Respond to any contract changes or requests that arise from financing issues
- Continue meeting the seller’s own deadlines and escrow requirements
7. Stay on top of contingency deadlines
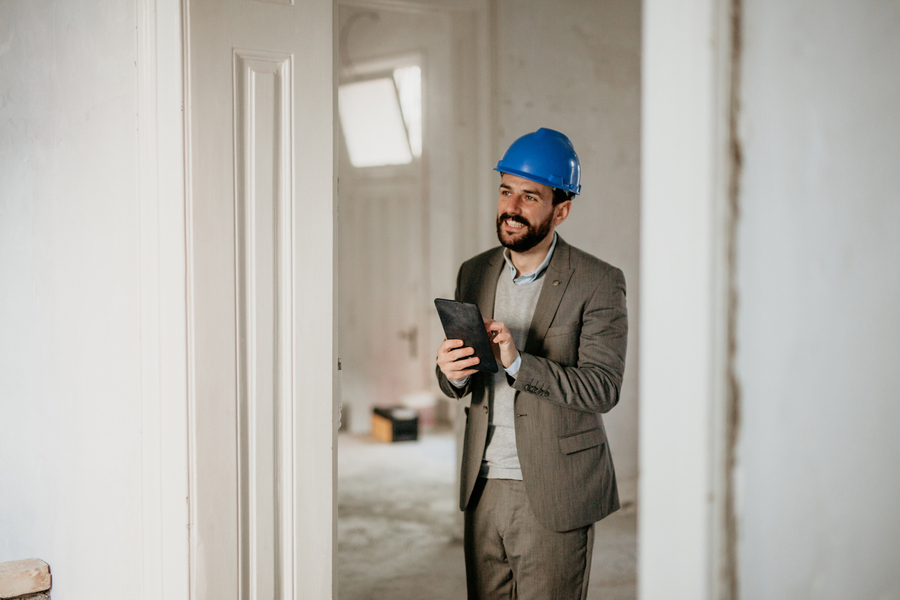
Don’t skip home inspection, as it can uncover issues that deserve a closer look before you complete the transaction.
Contingencies can protect buyers while they inspect the property, review documents, and complete financing. The exact contingencies, deadlines, and removal procedures depend on the signed purchase agreement, so neither side should treat them as automatic or interchangeable.
Contingencies might include the following:
- Property inspections and investigations
- Appraisal
- Loan approval
- Review seller documents and disclosures
- Title information
- HOA or community association documents
- Leased or liened items
What to keep top of mind:
- Know which contingencies apply and when each deadline falls
- Complete inspections, financing, and document review on time
- Discuss any concerns before removing or waiving a contingency
8. Negotiate what matters
Inspection findings can lead to repair requests, credits, price adjustments, or other solutions, depending on the contract. Not every small issue needs to be a negotiation. The goal is to focus on issues that could materially affect the property, your costs, or your plans for it.
What to keep top of mind:
- Prioritize structural, safety, major-system, and potentially costly issues
- Get estimates when repair costs could affect the decision
- Negotiate repairs, credits, or another solution allowed under the contract
9. Complete the final walkthrough
The final walkthrough lets the buyer confirm that the property is in the agreed condition before closing. It isn’t a new inspection or a chance to reopen every earlier issue.
What the buyer does:
- Confirm agreed-upon repairs were completed
- Check that included fixtures, appliances, and other items remain in place
- Look for new damage or other changes since the earlier inspections
What the seller does:
- Complete agreed-upon repairs and other obligations
- Remove personal belongings as required
- Leave the property in the condition required by the agreement
10. Sign, fund, and close escrow
Once the remaining conditions are satisfied, the final documents are signed, funds are delivered, and the deed is recorded. Escrow then closes, while possession and key delivery happen according to the purchase agreement.
At this stage:
- The buyer signs final documents and provides the required closing funds
- The seller completes the required transfer documents and any remaining payoff obligations
- Escrow handles the final disbursements and recording needed to complete the transaction
Get guidance on real estate due diligence in California
Every transaction brings its own questions, whether they involve disclosures, inspection findings, contingency deadlines, or closing details. The key is knowing what needs a closer look before you sign off.
I’ve helped buyers and sellers across Granada Hills and Los Angeles for more than two decades close their transactions with peace of mind.
Let me do the same for you. Call 818.606.6069 or send an email to get your free real estate consultation.